The Renewal That Costs 37% More for the Same Seats
By Alex
The procurement platform Tropic puts the number at 20 to 37 percent: the uplift enterprise software buyers are seeing at renewal, on contracts where the headcount hasn’t moved and nobody has asked for anything new. The mechanism isn’t a price rise in the ordinary sense. AI features get bundled into the tier you already have, or your SKU is migrated to a successor that includes them, and the line item arrives larger for the same seats. Tropic sells software procurement tooling, so treat the figure as interested rather than neutral — but the direction is corroborated everywhere, and the structural change underneath it is not in dispute.
Per-seat pricing is being dismantled. Gartner expects at least 40 percent of enterprise SaaS spend to sit in usage-, agent- or outcome-based models by 2030, with seat-based revenue falling from 21 percent of vendor income to 15. The pitch is that you stop paying for licences nobody logs into and start paying for work actually done. That part is true. The part that gets less airtime is what it does to who carries the forecasting risk.
What the seat was actually good at
The per-seat licence survived two decades of complaints about it, and it survived them because its critics and its defenders were arguing about different properties.
As a measure of value it was always poor. A seat that logs in twice a quarter costs the same as one running the business. Vendors watched customers extract wildly different returns from identical invoices and captured none of the difference.
As a measure of predictability, though, it was close to perfect, and predictability was the property the buyer was really paying for. Seat count changes slowly, changes visibly, and changes because the customer decided to change it. You can forecast next year’s bill from your hiring plan. Finance can approve it once and not think about it again. Nothing about consumption-based pricing preserves that. Volume is now set by how users and automated agents behave, which is not a number anyone approves in advance — and in the specific case of outcome pricing, the definition of the billable event is written by the vendor.
That is the actual trade. Not fairness for unfairness, but predictability for proportionality. It may well be worth making. It should at least be made knowingly.
The meter is being added, not swapped in
The framing of a “shift” from seats to usage suggests one model replacing another. Mostly it isn’t happening that way. Bain’s analysis of more than thirty major SaaS vendors found roughly 65 percent have layered an AI consumption meter on top of existing seat pricing.
Read that carefully, because it changes the arithmetic. If seats were replaced by consumption, a buyer would be trading a predictable bill for a variable one — bad for planning, but at least the variable part could go down in a quiet quarter. What is mostly being sold instead is the predictable floor plus a variable ceiling. The seat fee does not fall to make room for the meter. The best case is that you use nothing and pay what you paid before. Everything above that is new.
Among AI-native vendors the picture differs — Maxio puts usage-based adoption there at 83 percent — because those companies never had a seat base to protect. The incumbents are not converting. They are adding.
There is movement in the other direction too, which is worth noticing as a tell. Salesforce’s Agentic Enterprise License Agreement offers unlimited use of Agentforce, Data 360 and MuleSoft for a fixed fee on a two- or three-year term. That is a vendor selling predictability back to customers who have discovered they want it — at the cost of a multi-year commitment made before anyone knows what normal consumption looks like.
Who holds the counter
Outcome pricing runs into a problem that usage pricing mostly avoids: someone has to decide what counts.
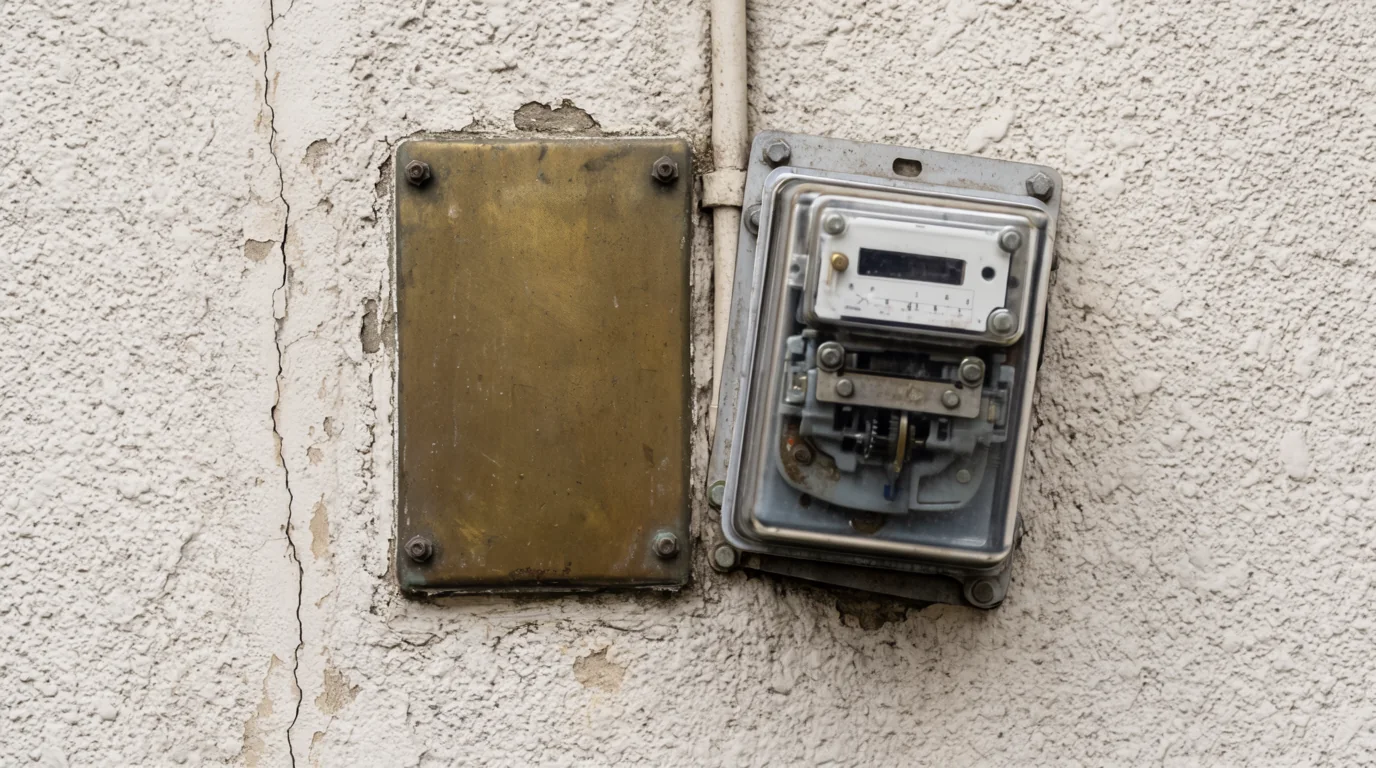
Zendesk was early and explicit here. In August 2024 it began charging per Automated Resolution — $1.50 for committed volume, $2.00 pay-as-you-go. A resolution is a defensible unit; a customer’s issue was handled without a human. But the vendor’s software decides whether a given interaction was a resolution, and the vendor bills for the answer. There is no independent meter, no regulated measurement standard, no equivalent of the sealed utility meter on a building wall. Intercom’s Fin agent, priced on the same logic, reported 393 percent annualised growth in a single quarter — revenue tied directly to a count the vendor computes.
The unit price is unstable too. Zendesk’s per-resolution price fell by roughly half within a year of launch under competitive pressure, which is a single-sourced figure but a plausible one for an early market. For a buyer that cuts both ways: the rate you negotiate this year may be well above the market rate next year, and unlike a seat price, there is no obvious public benchmark to argue from.
Even the accounting is unsettled. Deloitte published a technology spotlight on revenue recognition for outcome-based pricing in agentic products on 4 June 2026. When a category needs a fresh accounting treatment to explain when the vendor may recognise the money, the customer should not assume the measurement side has been solved either.
What to fix before the renewal window opens
The leverage in a SaaS contract exists in a narrow window and then closes. Once the renewal notice is out and the incumbent knows migration is impractical this quarter, the discussion is about discount percentage, not structure. The terms below are structural, which means they have to be raised early.
- Price protection with a real cap. An annual ceiling of 3 to 5 percent, or CPI indexing. Without it, “bundled AI features” is an unbounded justification for uplift.
- SKU-level price lock. A cap on the price of your current SKU does nothing if the vendor retires that SKU and migrates you to its successor. Lock the entitlement, not just the rate, and require consent for migration.
- Hard consumption ceilings. Not alerts — a contractual stop. Alerting tells you the bill grew; a ceiling is what prevents an integration bug from becoming a purchase order.
- An outcome measurement agreement. Written definition of the billable event, the right to see the underlying log data, and a dispute path when your count and theirs diverge. If a vendor will not define the unit in the contract, it is not a unit.
- A transition-to-usage clause. Agree now what happens if the vendor changes pricing models mid-term: whether you may stay on seats, and on what terms.
The reason to run this before the window rather than during it is that the answers are also a shortlist of vendors to worry about. A vendor that will cap uplift, define its unit and grant log access is a vendor whose pricing you can forecast. One that declines all five has told you something useful about the next three years, regardless of what the current invoice says.
The pattern this belongs to
Software isn’t the first category to discover that the billing unit is the whole negotiation. It isn’t even the first corner of software. Observability platforms went through it a few years earlier: teams priced on data volume and metric cardinality found their monitoring bills growing faster than the systems being monitored, and a 2026 survey of observability and platform engineering professionals found 53 percent had overrun budget by 10 percent or more. The failure mode was identical — a unit of consumption the customer could not see, could not forecast and did not directly control.
What follows is familiar from every other sourcing decision: the question stops being what a service costs and becomes who absorbs the variance when it changes. That is the same question behind choosing between managed and in-house IT, and the same one a managed services contract answers explicitly when it is written well. SaaS spent twenty years exempt from it because the seat count made the variance somebody else’s problem. That exemption is ending, and the renewal window is where each company finds out on which side of it they were standing.
- On September 24, 2026
- 0 Comment