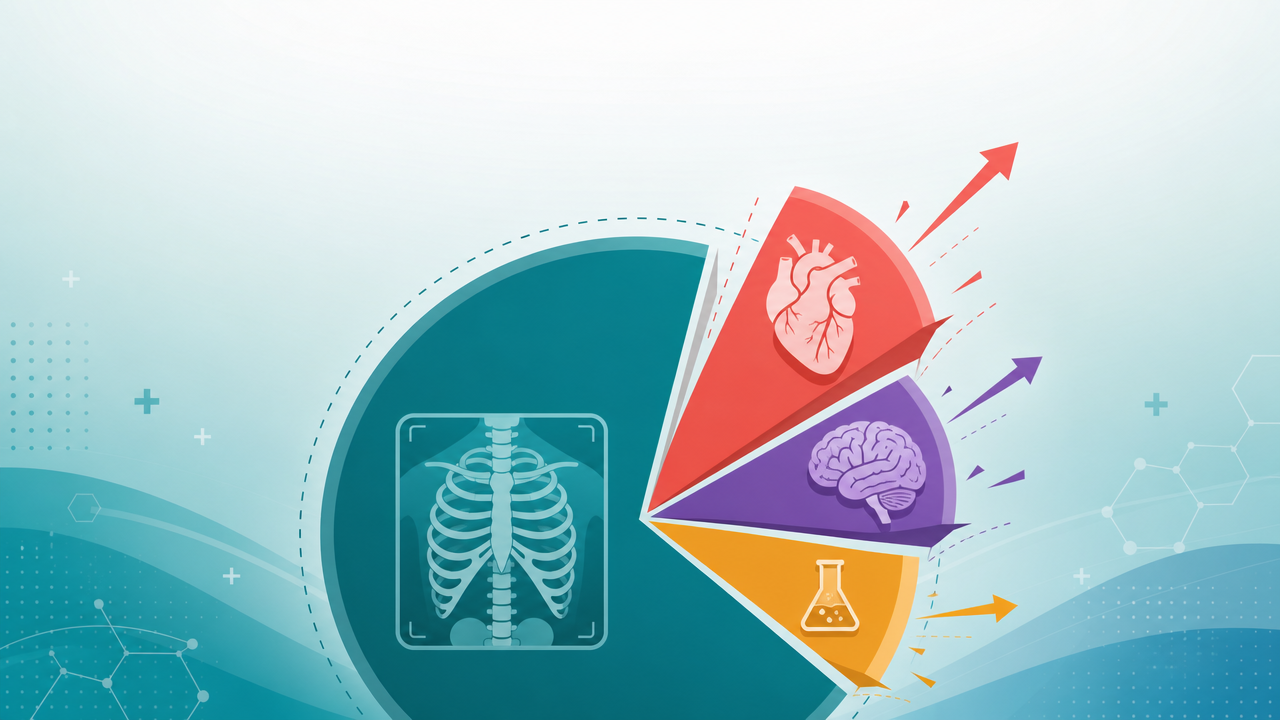
In 2015, the FDA cleared six AI-powered medical devices. In 2025, it cleared 295. By January 2026, the cumulative count of FDA-authorized AI medical devices had reached 1,357. Those numbers get cited constantly as evidence that healthcare AI has arrived — and they’re true, but they mostly restate something everyone already assumed. The more interesting number is buried a layer deeper: in 2026, radiology’s share of new AI device clearances dropped from 79 percent to 56 percent. After a decade of near-total dominance, the category that basically defined “AI medical device” is finally losing ground.
A Decade of One Specialty Carrying the Whole Category
Radiology has been the overwhelming center of gravity for FDA-cleared AI since the category existed in any meaningful volume. Depending on how the count is drawn, roughly 76 to 77 percent of all 1,357 cumulative authorizations sit in radiology — well over a thousand individual clearances for tools that read X-rays, CT scans, and MRIs. Cardiovascular devices come a distant second at 8.8 percent, neurology at 4.7 percent, with pathology, ophthalmology, and gastroenterology splitting a thin remainder.
The reason radiology got there first isn’t mysterious: medical imaging is naturally suited to the pattern-recognition strengths of the deep learning techniques that made this wave of AI devices possible in the first place. A model trained to spot a nodule on a chest CT is solving a problem with a similar shape to any other image-classification task — plentiful labeled data, a well-defined visual target, and a clear predicate lineage from earlier computer-aided detection software that FDA reviewers already had a regulatory framework for. Cardiology, neurology, and pathology present messier signal — physiological waveforms, multi-modal patient histories, tissue samples with more subjective interpretation — that took longer for AI tooling to mature into something clearable.
What Actually Changed in 2026
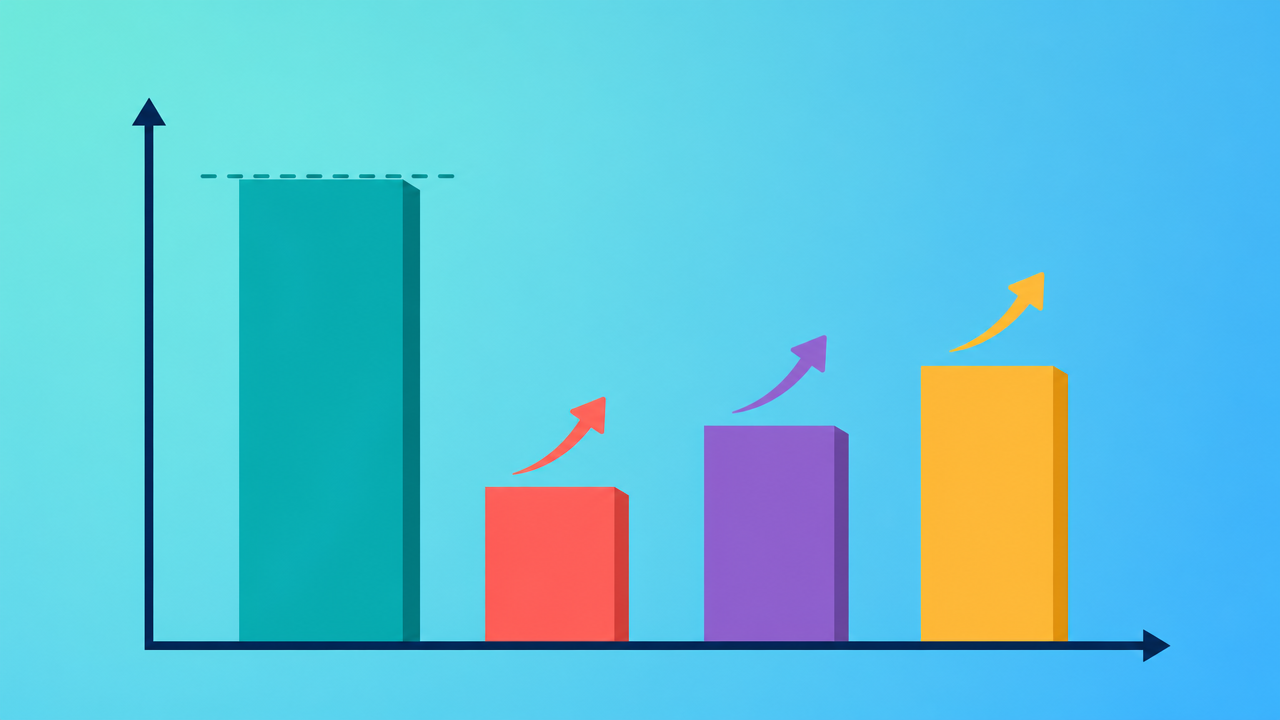
The shift from 79 percent to 56 percent in a single year is a much sharper move than a gradual trend line would predict, and it signals that the tooling gap between radiology and everything else narrowed faster than the historical pattern would suggest. Cardiovascular and neurology devices, still small in absolute cumulative share, are clearly taking a larger slice of *new* clearances specifically — which is the number that actually tells you where the field is heading, as opposed to the cumulative total, which will keep looking radiology-dominated for years simply due to the sheer volume already banked.
That distinction matters for anyone trying to read these statistics correctly: a cumulative share number describes the past. A share-of-new-clearances number describes momentum. By that measure, 2026 is the first year the data clearly shows non-radiology specialties gaining real ground rather than radiology simply continuing to compound its lead.
The Regulatory Pathway Question Underneath the Growth
The growth numbers invite a less celebratory read too. Most AI/ML device clearances go through the FDA’s 510(k) pathway, which authorizes a new device by showing it’s “substantially equivalent” to an already-cleared predicate device rather than requiring the more rigorous premarket approval process from scratch. That pathway works efficiently at scale — it’s a large part of why clearances could jump from 6 to 295 devices a year in a decade — but it also means many newer AI devices inherit their regulatory lineage from earlier, sometimes quite different, predicate software rather than each being independently validated against the same bar.
Critics have also flagged a more specific structural mismatch: FDA’s clearance framework was built around software with a fixed, static behavior at the time of approval, while a growing share of AI devices behave more like continuously updating systems whose outputs can drift as they encounter new data after deployment. A device cleared based on its behavior at one snapshot in time isn’t necessarily the same device, functionally, a year into real-world use — and the 510(k) predicate model doesn’t have a clean answer for how much drift is acceptable before a device needs to go back through review.
Why the Diversification Still Matters
None of that undercuts the more specific 2026 finding: whatever the pathway concerns, the fact that cardiology, neurology, and other specialties are picking up real share of new clearances means the AI-in-medicine story is no longer just “radiology, plus some noise.” A decade in, the technology and the regulatory muscle memory built around imaging AI appear to be transferring to specialties that presented harder technical problems — which is a genuinely different milestone than simply adding more radiology tools to an already-long list.